Posts

Showing posts with the label food inflation

Bitcoin sells off on higher US Producer Price Index, blowing out to 0.6% from 0.3% in January 2024. Yields and USD spike, sending the NASDAQ and BTC down from record highs.

Inflation humour. Pack of hazelnut sugar free (apparently), gluten free 'crunch' cereal. Economic rule of thumb, less purchasing power of the your country's currency, less portions of food. Pertaining to a country, like Australia with its currency soon-to-be worth half of the USD, that exports food at your expense. So, ask for a pay rise. Clip in post.

Self explanatory chart: Global food prices, with price increases for rice. Food inflation has not abated. Central Banks would play a risky game at pauses rates and/or cutting the cash rate. Particularly the U.S. Federal Reserve. All eyes USD bids and 10 YR yields, which could land at 5% on sticky/rising inflation. The 'soft-landing' scenario should be replaced with stagflation.
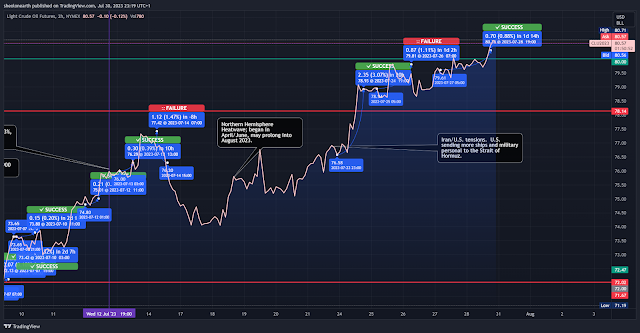
Oil hits $80 as markets begin to price in tighter supply and geopolitical concerns. Food inflation shock is on the way as Corn, Rice and Wheat futures are all bid (supported) above May 2021 highs.

Inflation shock: Corn, Wheat and Oil futures rally between 10% and 18% as traders begin to lock in prices. Re: Northern Hemisphere heatwave and the Russian 2023 'blockade' of Black Sea/Ukrainian ports. Also, Russian missile attacks of Ukrainian grain silos.

Wheat futures return to their April 2021 highs before the price went parabolic re: Russian invasion of Ukraine in February 2022. Any political destabilization in Russia may have a drastic spill over effect on wheat and grain prices.

Are Central Banks on an end year pause with rates hikes as they bounce around with Dovish and Hawkish rhetoric? Inflation could become hyperinflation in 2023 with Central Bank's lack of guidance to the market. The Fed's terminal rate should be at 9%

The Pound sterling collapses to its 37 year lows, the U.K. is facing inflation, recession and an energy crisis mixed with parabolic debt levels.

U.S. CPI blows out to a four decade high at 9.2%. Inflation rate is now reaching double digit numbers, while Central Banks are still sitting on low rates. The situation, economically is dire.

Oil futures are now in a bear market, declined over 20%. The price is now showing up as a recession/stagnation based beatdown. Final price support at $94. OVX (oil volatility) is beginning to pick up.

The YEN collapse is pointing towards an inflationary crisis in Japan rather than deflationary. Japanese consumer costs are skyrocketing, while the Bank of Japan keeps rates at ultra-low levels. Could Japan be one of the first major economies to priced out of existence?

U.S Consumer Price Index blows out at 8.3%. Estimates were at a declining peak of 8.1%. Oil, gas, food and electricity prices are now parabolic in a correlated incline. Central Bank reluctance to trigger above 2% rate increases maybe about to change. We could witness a dramatic lifting of rates throughout 2022.

Central Banks slowly beginning an interest rate cycle, lead by the Federal Reserve. Rate now at 1.00%, low compared to past cycles, amidst the global food and energy inflation crisis. The fear of higher rates and slowing economy may be a force of hand play if oil stays above $100 USD. Central banks have not priced in stagflation.

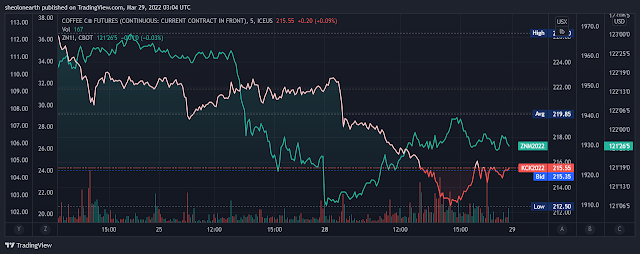
The correlation of Coffee prices and the U.S 10 Year Treasury note.

Markets of debt and the Food Inflation shock.